Employer sponsored health plans cost you more than the payroll deduction suggests. Your real yearly spending is the sum of your share of the premium, the deductible, copays and coinsurance you pay when you use care, plus anything the plan does not cover. Knowing how those pieces fit together lets you pick the right plan during open enrollment and avoid surprise bills. This guide explains each cost with simple examples.
Key takeaways
- Total cost = your premium share + out-of-pocket spending + uncovered costs.
- A lower premium often means a higher deductible, so compare total possible cost, not just the paycheck deduction.
- Adding family members to coverage usually raises your share of the premium significantly.
- HSAs and FSAs can reduce taxes on medical spending if you qualify.
- Always check whether your doctors and prescriptions are in the plan’s network and formulary.
The parts of the bill you actually pay
Premium
With employer sponsored health plans, the premium is only the first cost. The premium is the monthly price of coverage. With employer plans, your employer pays a portion and the rest is deducted from your paycheck, often before taxes. Employers typically contribute more towards employee-only coverage than towards family coverage, so adding a spouse or children can raise your share noticeably.
Deductible
The deductible is the amount you pay for covered services before the plan starts paying its share. Preventive care is often covered before you reach it, but many other services are not. A plan with a deductible of a few thousand dollars means a hospital stay early in the year costs you far more than the same stay late in the year after you have already met it.
Copays and coinsurance
Copays are fixed fees, such as a set amount for a doctor visit. Coinsurance is a percentage of the cost, such as 20 percent of a procedure after the deductible is met.
Out-of-pocket maximum
This is the most you will pay in a plan year for covered, in-network care. After you reach it, the plan covers 100 percent of covered services. It is your protection against catastrophic costs. For plain-language definitions, see our guide to health and medical insurance terms that cost you real money.
How employer plan types differ
Most employer sponsored health plans fall into a few designs. Most employers offer a handful of plan designs. The details vary, but the trade-offs are consistent.
- HMO: usually lower costs but requires you to use a network and often a referral from a primary care doctor.
- PPO: more freedom to see out-of-network providers at higher cost, with typically higher premiums.
- EPO: network-only like an HMO, but often without the referral requirement.
- High-deductible health plan (HDHP): lower premiums, higher deductible, and often eligible for a health savings account.
The official site HealthCare.gov glossary explains these terms in detail and is a reliable reference when you are comparing options.
A worked example (illustrative numbers)
Imagine two plans offered by the same employer. Plan A has a lower premium and a high deductible; Plan B has a higher premium and a small deductible. These figures are only an example to show the method, not real prices.
| Item | Plan A (HDHP) | Plan B (PPO) |
|---|---|---|
| Your yearly premium | $1,200 | $2,400 |
| Deductible | $3,000 | $500 |
| Out-of-pocket maximum | $5,000 | $3,500 |
| Worst-case yearly cost | $6,200 | $5,900 |
If you are healthy and rarely see a doctor, Plan A may cost less overall. If you expect surgery, a pregnancy or regular specialist visits, Plan B may save money despite the higher premium. Compare best case, typical case and worst case before choosing.
Tax-advantaged accounts
Many employer sponsored health plans come with accounts that lower your tax bill. Many employers offer accounts that lower your tax bill on medical costs. A health savings account (HSA) works alongside a qualifying high-deductible plan; contributions can roll over year to year. A flexible spending account (FSA) lets you set aside pre-tax money for eligible expenses but often has a use-it-or-lose-it rule or limited carry-over. Check current limits and rules with the plan administrator or the IRS, because they change every year.
Costs people forget
- Out-of-network care: some plans pay little or nothing for providers outside the network.
- Prescription tiers: brand-name or specialty drugs can fall into higher-cost tiers.
- Prior authorisation: skipping a required approval can lead to denied claims.
- Dependent coverage: a spouse with access to their own employer plan may be cheaper to cover separately.
- Surprise bills: verify that facilities and the clinicians working there are in network.
- List your expected care for the year: regular medicines, planned procedures and specialist visits.
- Check that your doctors, hospital and pharmacy are in network.
- Calculate yearly premium plus likely out-of-pocket costs under each plan.
- Look at the out-of-pocket maximum as your worst-case protection.
- Consider tax accounts and any employer contribution to an HSA.
- Read the summary of benefits and coverage, which employers must provide.
Even careful buyers of employer sponsored health plans miss these costs.
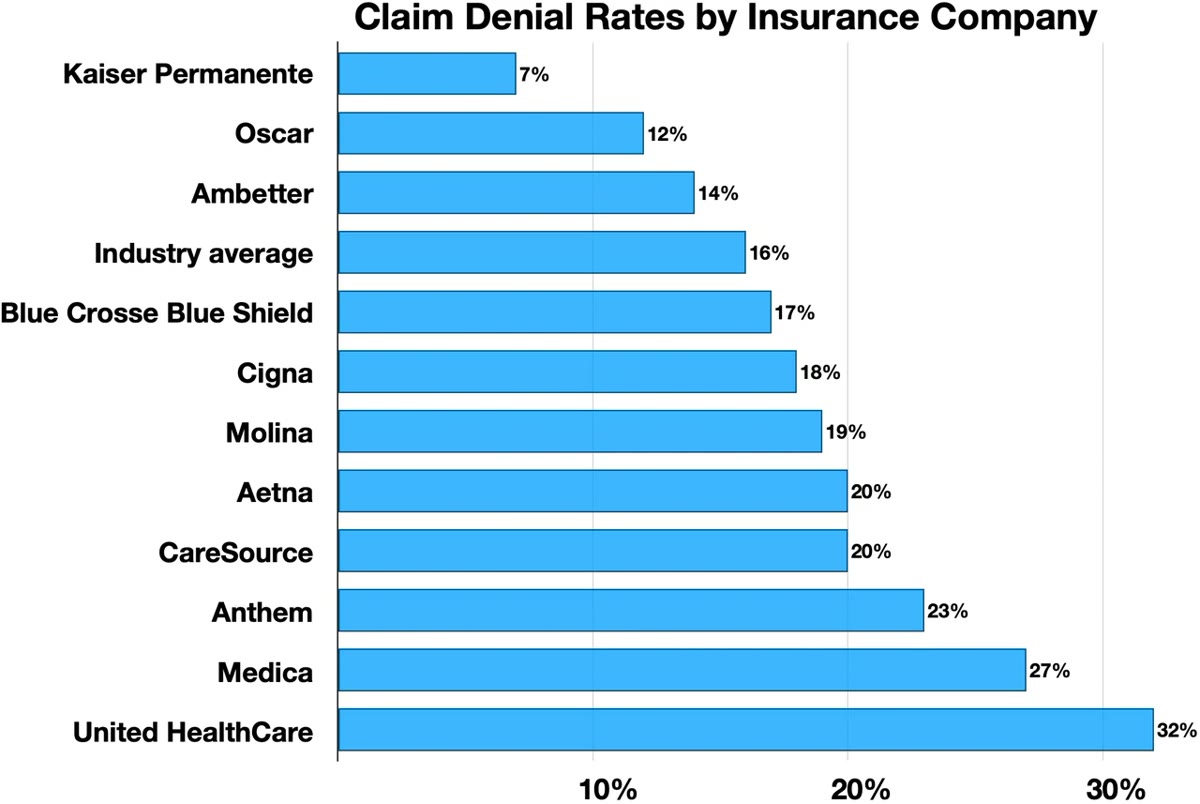
Denials happen, and appeals are worth the effort. Industry research on how often claims are denied varies by insurer, so keep documentation of every call and bill.
How to compare plans during open enrollment
For broader trends in employer premiums and contributions, the annual KFF health costs research is a respected independent source. Employers who want healthier teams also look beyond insurance, as shown by executive health programmes aimed at preventing problems.
Frequently asked questions
Why are employer sponsored health plans cheaper than buying alone?
Employers typically pay part of the premium and spread risk across a group, and employee contributions are often made before taxes.
What is the difference between a deductible and an out-of-pocket maximum?
The deductible is what you pay before the plan begins sharing costs; the out-of-pocket maximum is the cap on what you pay in a year for covered care.
Is a high-deductible plan a bad idea?
Not necessarily. It can suit healthy people who use an HSA, but it can strain budgets if big medical costs arrive.
Can I change plans during the year?
Usually only during open enrollment or after a qualifying life event such as marriage, birth or loss of other coverage.
Do I have to cover my spouse?
No. Compare your spouse’s own employer options, because covering them separately is sometimes cheaper.
Conclusion
Employer sponsored health plans are valuable, but their true cost includes premiums, deductibles, copays, coinsurance and gaps in coverage. Model your likely year, compare the worst case, and confirm networks before choosing. A little arithmetic at enrollment can save thousands later.